


Call Us
+86-19518020980
Email Us
chloe@kebonfirstaid.com
Why AI Cargo Is Pushing Up First Aid Kit Freight Costs
1. Your freight got more expensive. The reason is not your cargo.
If you import first aid kits, your product has not changed. Your freight bill has — and the fastest-growing force behind it has nothing to do with medical products at all.
Through late 2026, the dominant new demand in global logistics is artificial intelligence infrastructure: servers, GPUs, power equipment, cooling systems and the high-value electronics that build data centres. DHL's global freight leadership estimates that roughly two-thirds of AI-related high-value products move by air. Air cargo indices have broken above the last two peak seasons — the Baltic Air Freight Index was running about 26 percent above the previous year as of October, driven substantially by this trade. And the effect does not stop at the aircraft door: the same supply chains pull on ocean capacity, container equipment and port handling across Asia.
The result is a structural squeeze that has little to do with the products ordinary importers ship. A first aid kit competes for the same vessel slot, the same container, the same terminal window as a rack of AI servers — and when the other cargo is worth a hundred times more per kilogram, guess whose freight the market prices first.
This article explains what is actually happening, what the numbers say as of early November 2026, and — more usefully — what a first aid kit importer can do about a cost pressure caused by someone else's cargo.
2. The numbers, as of early November 2026
We track these weekly for our own shipping programme, so let us put the figures on the table with their dates.
Ocean: falling from the peak, still far above normal. Drewry's World Container Index slipped about 3 percent in the last week of October to roughly USD 4,429 per FEU — but that composite remains about 143 percent above the same week a year earlier. The transpacific lanes tell the sharper story: Shanghai to Los Angeles around USD 7,514 (still roughly 208 percent above a year ago) and Shanghai to New York around USD 9,631 (up about 170 percent year on year). Asia–Europe is softer — Shanghai–Rotterdam near USD 3,686, Shanghai–Genoa USD 4,151 — with carriers pushing FAK increases of USD 4,200–4,500 per FEU from mid-October and Maersk announcing a further Far East–North Europe/Med increase effective 16 November. The Middle East remains its own story: Shanghai to Jebel Ali sits near USD 8,584 as Gulf disruptions persist, and only a trickle of vessels — about two a week — transit the Strait of Hormuz even as Suez transits hit their highest weekly figure of the year.
Air: the tightest market of the three. Air freight out of China has seen repeated rounds of rate increases since factories reopened after Golden Week. The demand signal is structural, not seasonal: AI hardware is heavy, urgent, high-value and largely air-dependent, and it is bidding for belly and freighter capacity against everything else. For a category like first aid kits — bulky relative to value — the air market matters as the emergency valve, and the valve is expensive.
Demand side: softer, but not soft. The US National Retail Federation expects ocean imports to fall about 11 percent month on month in November as retailers finish front-loading, and blank sailings are scheduled across the transpacific. Carriers are managing capacity actively, which supports rates even as volume dips. Meanwhile intra-Asia rates are running roughly 200 percent above last year — the regional components trade feeding Asian manufacturing is hot, and it affects component costs too, not just freight.
The layer underneath: tariffs and fees. Cargo costs are not only freight. As of writing, 178 Section 301 product exclusions expire on 9 November 2026 with no extension announced, and the separate suspension of maritime service fees on China-linked vessels has a proposed extension to 9 January 2027 that is not yet finalised. We cover the tariff mechanics in detail here — read that alongside this article, because freight and duty decisions interact.
3. Why AI cargo squeezes everyone else
It is worth understanding the mechanism, because it tells you which pressures are temporary and which are not.
Value density sets the price hierarchy. A kilogram of AI hardware can be worth hundreds or thousands of dollars; a kilogram of first aid kits is worth a few dollars. When high-value cargo is abundant, it can absorb rates that would make low-value cargo uneconomic. Air freight prices up first, then shippers who cannot pay divert to ocean, then ocean absorbs the overflow and its rates follow. The chain works top-down by value.
The AI trade is time-critical, so it does not wait. Data centre projects run on construction schedules and compute-hunger, not retail calendars. This demand does not disappear in a post-peak soft patch — it just keeps tendering. That is why air indices are breaking above previous seasonal highs in what should be a mixed window.
Capacity is not responding quickly. Aircraft deliveries are constrained, vessel orders take years, and the tonnage that returned to Suez routing is being absorbed by the demand growth rather than easing it. Meanwhile geopolitical facts — Hormuz effectively restricted, Red Sea recovery partial — keep a risk premium on everything from bunker costs to insurance.
For a bulky, value-dense product like a first aid kit, the squeeze is double. Kits are "light" cargo in the value sense but "heavy" in the cube sense: large cartons, low value per cubic metre. You are paying for volume in a market where volume is what the high-value trade is crowding. This is the structural disadvantage — and the reason volume management, not just freight negotiation, is the importer's best lever.
The honest read: some of this pressure is cyclical and some is structural. The cyclical part will ease as data centre buildouts digest; the structural part — higher baseline demand for capacity from a new class of cargo — is now part of the planning picture for 2027.
4. Seven practical moves for first aid kit importers
None of the levers below requires changing suppliers. All of them require treating freight as a designed input rather than a quoted afterthought.
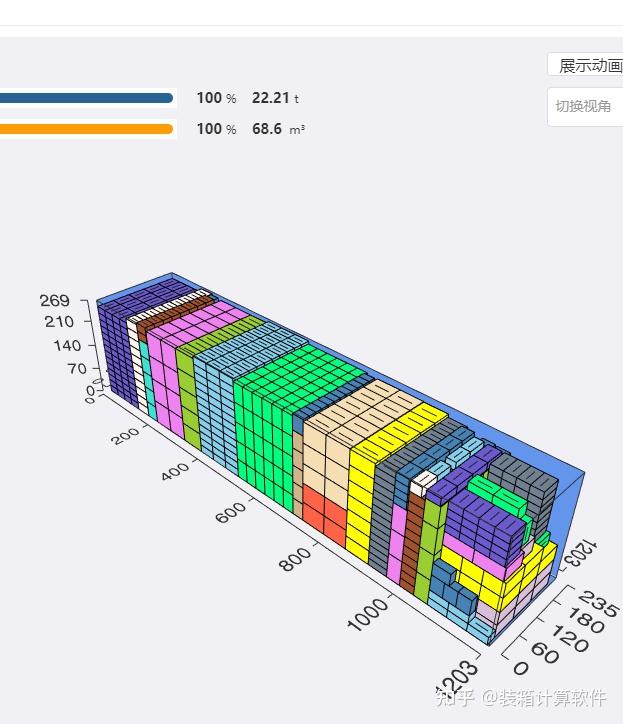
1. Optimise the cube before you negotiate the rate. When your cost per container is elevated, every cubic centimetre matters. Ask whether the same kit ships in a tighter carton, with less void fill, or with vacuum-compressed soft components. A five percent carton reduction across a container is real money at current rates — and unlike a negotiated discount, it compounds on every shipment for years.
2. Split the programme by urgency, not by habit. Most kit volume does not need to move fast. Identify the genuinely urgent fraction — launch stock, stockout cover, compliance-driven content updates — and reserve air freight for it deliberately. Let the base programme ride ocean without apology.
3. Book earlier than feels necessary. With carriers blanking sailings and managing capacity, lead times for space have widened even when vessel transit is unchanged. Two to three weeks of booking lead time is the new normal on the transpacific; late bookings pay both the higher rate and the rollover risk.
4. Read the validity clauses on your quotes. In a market of repeated GRI and PSS announcements, a rate is only as durable as its validity window. Make sure your quotation covers you through loading, and know which surcharges can be applied to bookings already made.
5. Watch the Middle East premium if you ship to the Gulf. With Shanghai–Jebel Ali near USD 8,584 and Hormuz transits minimal, Gulf-bound cargo carries both a rate premium and schedule uncertainty. If the Gulf is part of your programme, plan around it rather than discovering it at booking — our earlier piece on Middle East shipping and order planning covers the compliance side of that market.
6. Put the duty and freight decisions in one conversation. The cheapest freight routing can be undone by a duty treatment that depends on entry timing. With the 9 November exclusion deadline and the vessel-fee extension unresolved as we write, landed-cost maths needs both layers — see our tariff deadline analysis before you fix Q1 routings.
7. Re-examine packaging weight as well as volume. Carton board, void fill and packaging weight all cost money at current rates. This is a design-stage decision with a freight payoff — one more reason packaging belongs in the specification conversation with your factory, not in the artwork stage after it.
5. How we help control the cube
Freight is not our business — but shipping efficiency is part of how we quote, because our buyers pay it.
Carton optimisation is a standard part of our quotation. We provide carton dimensions, gross weights and kits-per-container alongside unit pricing, so you can compare programmes on landed cost rather than unit cost. Where a configuration allows a smaller carton without compromising the kit's protection or presentation, we will propose it.
Honest ex-works dates keep your bookings real. A booking made against a slipped production date costs a rollover. Our delivery dates are production-verified before you commit freight, and we would rather tell you a real date now than a convenient one that fails later.
Consolidation across a broad range. Because we manufacture workplace kits, car emergency rescue kits, tactical packs and consumables on one production base, programme buyers can consolidate mixed orders into fewer containers — fewer bookings, fewer fees, better cube utilisation.
Planning 2027 volumes against elevated freight? Send us your kit list and target shipment windows — we will come back with carton data, container plans and honest production dates so you can price the whole landed cost, not just the unit.
6. The year ahead
Nobody can call freight rates, and we will not pretend to. But the direction of the structural forces is legible: AI-related demand has added a large, price-insensitive tenant to global logistics that did not exist at this scale two years ago; geopolitical routing constraints keep a floor under costs; and the capacity response is slow. For low-value-density cargo like first aid kits, the planning implication is simply this: the freight line in your landed cost deserves the same engineering attention as the product itself.
The importers who will do well in 2027 are not the ones who guess the market right. They are the ones whose packaging is tighter, whose urgent/regular split is deliberate, whose bookings lead their production, and whose supplier quotes container data as a matter of course. That is a controllable list — and every item on it is available to you now.
7. FAQ
Why is my freight still expensive when headline rates have been falling?
Headline composites mix all routes. Year on year, the transpacific and intra-Asia lanes remain far above prior-year levels, and your actual rate depends on route, service, equipment type and validity window. Falling from a peak is not the same as returning to normal.
Is air freight ever worth it for first aid kits?
For specific, limited purposes: launch stock, stockout cover, or urgent compliance-driven content updates. At current air rates it is a precision tool, not a baseline strategy — and the volume optimisation advice above matters most for the base programme that stays on the water.
Do tariffs affect my freight rate?
Indirectly, yes. Duty exposure changes what is worth shipping and when, and the suspension of fees on China-linked vessels — if it lapses — would raise carriers' costs on affected services, which historically pass through into rates and surcharges. Keep the two conversations together.
How much can carton optimisation really save?
It depends on the product, but savings of a few percent in container utilisation are common when packaging is designed with freight in mind rather than around it. At rates still far above historical norms, that difference compounds across every shipment.
Can Kebon provide container loading data before I commit an order?
Yes — carton dimensions, gross weights and container plans are part of our standard quotation. Ask for them with your next quote request.
Send Inquiry
X
We use cookies to offer you a better browsing experience, analyze site traffic and personalize content. By using this site, you agree to our use of cookies.
Privacy Policy
News
 After 9 November: New Landed Costs for First Aid Kits2026/11/03
Whether or not the 178 Section 301 exclusions are extended, your landed cost math changes. Three scenarios for first aid kit importers, with the numbers.
 Why AI Cargo Is Pushing Up First Aid Kit Freight Costs2026/11/03
AI hardware now crowds air and ocean capacity, lifting freight costs for ordinary cargo like first aid kits. What importers can do about it in 2027